Scientific research association approval requires continuing SIRO status, annual donation reporting, and donor certificates for the approved foundatio...
Scientific research institution approval is conditional on SIRO recognition, annual donation reporting, donor certification, and prescribed compliance...
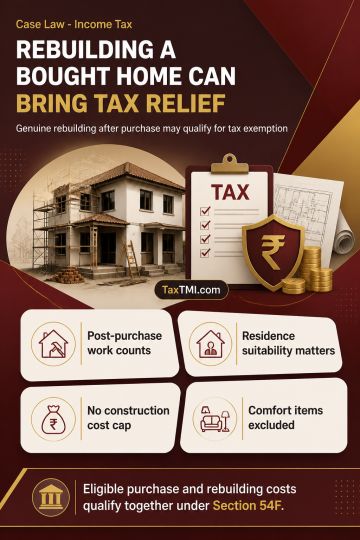
Section 54F permits exemption based on investment in a residential house through purchase, construction, or a combination of both. The cost of the new asset can include bona fide expenditure incurred after purchase for reconstruction, alteration, renovation and improvements that make the house fit for residence. Habitability of the purchased house and reconstruction expenditure exceeding its purchase cost do not independently restrict the exemption, as no statutory ceiling applies to construction quality or amenities. Expenditure on independent comfort items remains excluded. Where reconstruction expenditure is genuine and not linked to excluded items, the aggregate purchase and reconstruction cost qualifies for the Section 54F exemption.
Section 54F permits exemption based on investment in a residential house through purchase, construction, or a combination of both. The cost of the new asset can include bona fide expenditure incurred after purchase for reconstruction, alteration, renovation and improvements that make the house fit for residence. Habitability of the purchased house and reconstruction expenditure exceeding its purchase cost do not independently restrict the exemption, as no statutory ceiling applies to construction quality or amenities. Expenditure on independent comfort items remains excluded. Where reconstruction expenditure is genuine and not linked to excluded items, the aggregate purchase and reconstruction cost qualifies for the Section 54F exemption.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881