Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Page of 4884
Press 'Enter' after typing page number.
261 to 280 of 97661 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
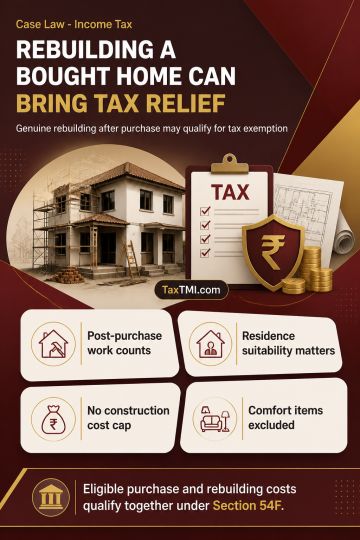
Section 54F permits exemption based on investment in a residential house through purchase, construction, or a combination of both. The cost of the new asset can include bona fide expenditure incurred after purchase for reconstruction, alteration, renovation and improvements that make the house fit for residence. Habitability of the purchased house and reconstruction expenditure exceeding its purchase cost do not independently restrict the exemption, as no statutory ceiling applies to construction quality or amenities. Expenditure on independent comfort items remains excluded. Where reconstruction expenditure is genuine and not linked to excluded items, the aggregate purchase and reconstruction cost qualifies for the Section 54F exemption.
Section 54F permits exemption based on investment in a residential house through purchase, construction, or a combination of both. The cost of the new asset can include bona fide expenditure incurred after purchase for reconstruction, alteration, renovation and improvements that make the house fit for residence. Habitability of the purchased house and reconstruction expenditure exceeding its purchase cost do not independently restrict the exemption, as no statutory ceiling applies to construction quality or amenities. Expenditure on independent comfort items remains excluded. Where reconstruction expenditure is genuine and not linked to excluded items, the aggregate purchase and reconstruction cost qualifies for the Section 54F exemption.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884