Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
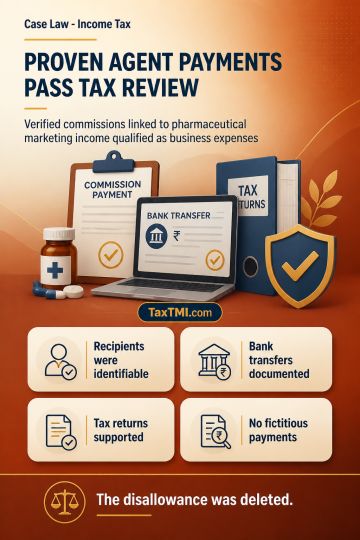
Commission payments to agents were allowable as business...
Commission expenditure linked to pharmaceutical marketing income qualifies as business deduction when recipient identity, genuineness and business purpose are established.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Commission payments to agents were allowable as business expenditure where they were intrinsically linked to commission income earned from pharmaceutical companies for facilitating marketing and sales. The disallowance based on an assumption that payments related to direct sales to Government hospitals lacked factual support. Recipient details, tax deduction at source, banking-channel payments and recipients' income-tax returns established the identity of recipients, genuineness of payments and business purpose. With no evidence of fictitious payments, non-existent recipients or diversion back to the assessee, the expenditure satisfied the wholly and exclusively business-purpose test and the disallowance was deleted.
Commission payments to agents were allowable as business expenditure where they were intrinsically linked to commission income earned from pharmaceutical companies for facilitating marketing and sales. The disallowance based on an assumption that payments related to direct sales to Government hospitals lacked factual support. Recipient details, tax deduction at source, banking-channel payments and recipients' income-tax returns established the identity of recipients, genuineness of payments and business purpose. With no evidence of fictitious payments, non-existent recipients or diversion back to the assessee, the expenditure satisfied the wholly and exclusively business-purpose test and the disallowance was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881