Judicial review of settlement orders cannot reopen settled customs notices, while statutory interest remains subject to verification and quantificatio...
Customs Broker licence lending for consideration justified revocation where exporter authorisation and client verification obligations were also breac...
Fraudulent import documents suspend limitation protection, while redemption of confiscated goods requires duty and interest despite bona fide purchase...
ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
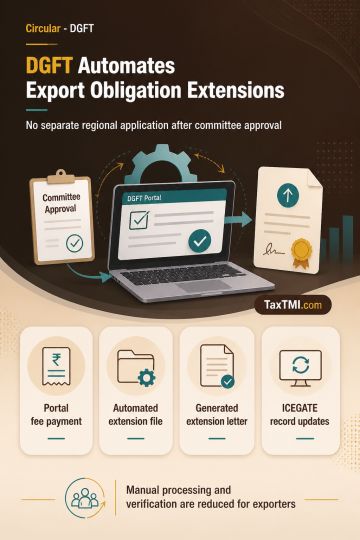
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
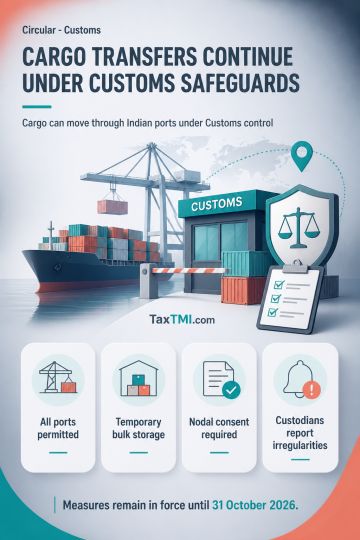
International cargo transhipment through Indian ports continues with Customs-controlled storage, re-export safeguards, and coordinated multi-station m...
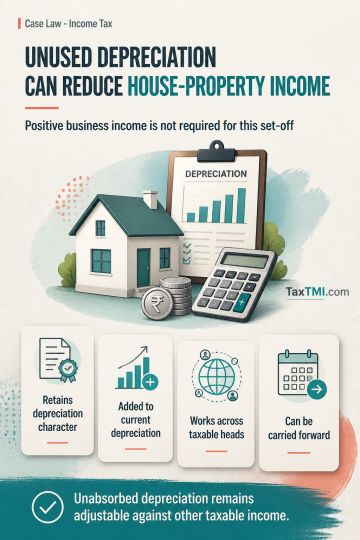
Brought-forward unabsorbed depreciation is added to current-year depreciation and retains the character of depreciation, allowing set-off against income under other taxable heads. Its availability does not depend on the existence of positive business income. Accordingly, unabsorbed depreciation may be set off against income from house property, consistent with the principle that it can be carried forward and adjusted against other taxable income.
Note: It is a system-generated summary and is for quick reference only.