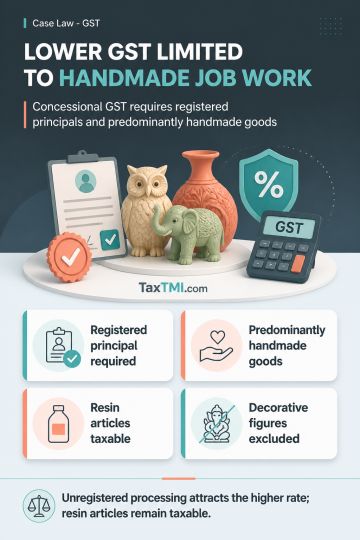
Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Profits from an eligible windmill unit's electricity transferred for captive consumption qualify for deduction under section 80IA. The profit must be computed using the rate charged by the Electricity Board to consumers, rather than the lower rate paid by the Board to generating companies. Payments were not liable to disallowance merely because payees could not be produced after a substantial lapse of time or because expenditure had increased over earlier years. The nature of payees, including labourers, contractors and job workers, and the fact that several payments were below the tax-deduction threshold, precluded treatment of the payments as unexplained. Deduction for captive wind-generated electricity and the payment claims were consequently accepted.
Profits from an eligible windmill unit's electricity transferred for captive consumption qualify for deduction under section 80IA. The profit must be computed using the rate charged by the Electricity Board to consumers, rather than the lower rate paid by the Board to generating companies. Payments were not liable to disallowance merely because payees could not be produced after a substantial lapse of time or because expenditure had increased over earlier years. The nature of payees, including labourers, contractors and job workers, and the fact that several payments were below the tax-deduction threshold, precluded treatment of the payments as unexplained. Deduction for captive wind-generated electricity and the payment claims were consequently accepted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935