Co-operative deduction eligibility excludes refund and commercial-bank interest, while qualifying co-operative investments require entity-wise verific...
Enhanced tax rate on surrendered unexplained income applies prospectively, while cash-deposit telescoping requires verification of available surrender...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory act...
Provisional assessment finalisation must precede export duty recovery, while redemption fine fails for goods already exported and unavailable for conf...
Page of 4896
Press 'Enter' after typing page number.
1921 to 1940 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
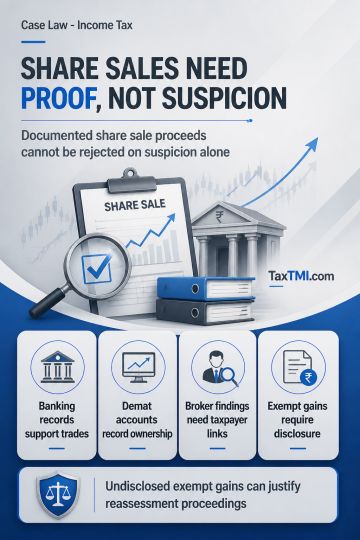
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896