Section 115BBE classification requires a valid deeming-provision basis before special taxation, while the enhanced rate's temporal application remains...
Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
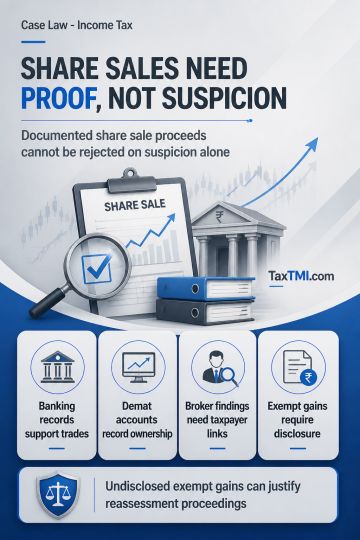
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894