Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
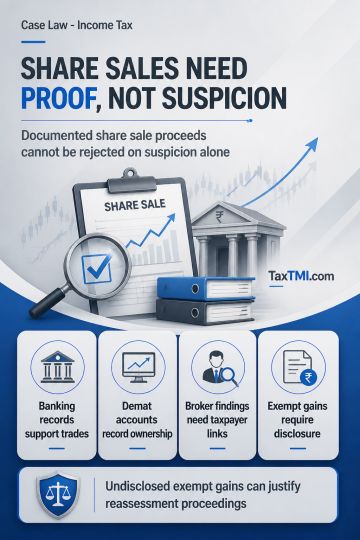
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881