Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
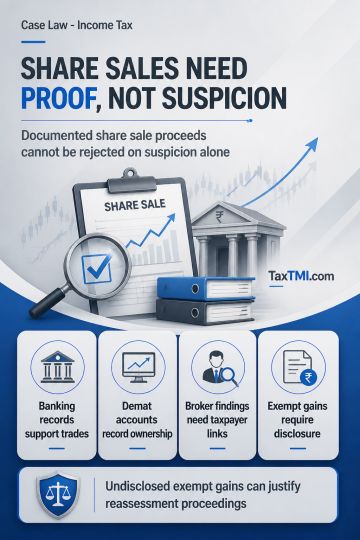
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881