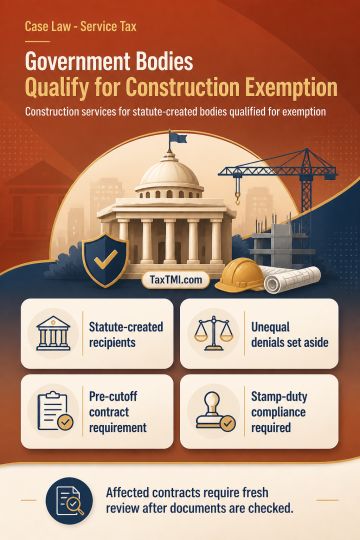
Governmental authority status supports construction-service exemption, while pre-cutoff contract and stamp-duty compliance requires verification on re...
Automated Free Sale and Commerce Certificates enable paperless processing while retaining risk-based manual verification for selected exporter applica...
Employee stock-shortage penalties do not constitute consideration for services, preventing GST collection under Schedule II in employment relationship...
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Penny-stock share sale proceeds cannot be treated as unexplained money merely on suspicion of accommodation entries where purchases and sales occurred through banking channels, demat accounts and the stock exchange. Investigation findings about broker manipulation require material linking the taxpayer to bogus purchases, cash exchanges, price rigging or an entry arrangement; absent such evidence, documentary transaction records prevail and the addition is unsustainable. Exempt long-term capital gains nevertheless require disclosure through a return, and failure to file a return for the relevant year can justify reassessment proceedings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929