Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
Investigation deposits refunded after failed customs demands fall outside the statutory appellate pre-deposit interest regime and may attract compensa...
Resolution plan finality extinguishes unquantified operational-creditor claims and pending proceedings unless the approved plan expressly preserves th...
Page of 4897
Press 'Enter' after typing page number.
661 to 680 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
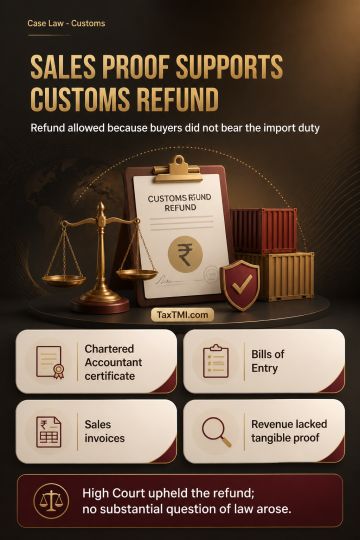
Unjust enrichment does not bar a customs-duty refund where evidence establishes that the duty incidence was not passed to buyers. A Chartered Accountant certificate, Bills of Entry and sales invoices showing bunker oil was sold below its import value supported non-recovery of even the import cost. Once that material was produced, Revenue needed tangible evidence that buyers bore the duty; recording duty as expenditure in the profit and loss account was insufficient. The High Court upheld the finding that the importer had not passed on the duty incidence, so the refund was properly allowed and no substantial question of law arose.
Unjust enrichment does not bar a customs-duty refund where evidence establishes that the duty incidence was not passed to buyers. A Chartered Accountant certificate, Bills of Entry and sales invoices showing bunker oil was sold below its import value supported non-recovery of even the import cost. Once that material was produced, Revenue needed tangible evidence that buyers bore the duty; recording duty as expenditure in the profit and loss account was insufficient. The High Court upheld the finding that the importer had not passed on the duty incidence, so the refund was properly allowed and no substantial question of law arose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897