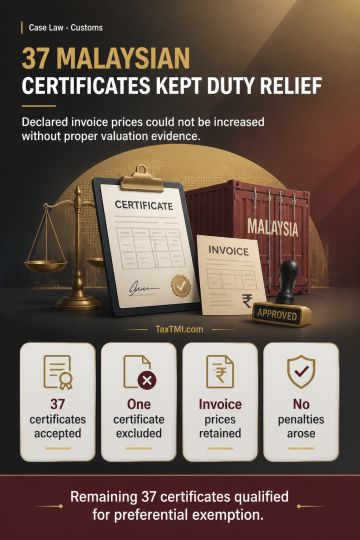
Country of Origin Certificates and declared transaction value supported preferential customs exemption where authenticity and invoice prices remained ...
Online bond platforms may offer overseas-regulated products and tax-specific bonds subject to disclosures, compliance safeguards and revised complianc...
Corporate guarantee valuation permits actual ascertainable commission while barring retroactive application and extended-period penalties for bona fid...
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through w...
Transitioned CENVAT credit may validly satisfy mandatory pre-deposit requirements for legacy service tax appeals through Electronic Credit Ledger debi...
Page of 4896
Press 'Enter' after typing page number.
2021 to 2040 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
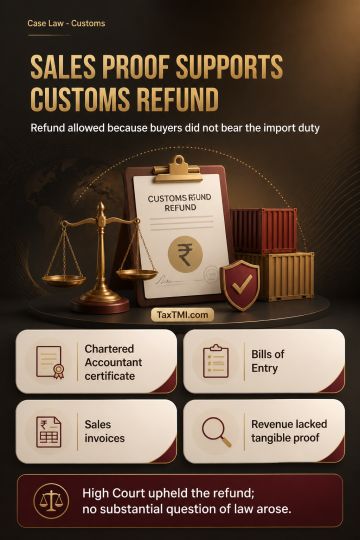
Unjust enrichment does not bar a customs-duty refund where evidence establishes that the duty incidence was not passed to buyers. A Chartered Accountant certificate, Bills of Entry and sales invoices showing bunker oil was sold below its import value supported non-recovery of even the import cost. Once that material was produced, Revenue needed tangible evidence that buyers bore the duty; recording duty as expenditure in the profit and loss account was insufficient. The High Court upheld the finding that the importer had not passed on the duty incidence, so the refund was properly allowed and no substantial question of law arose.
Unjust enrichment does not bar a customs-duty refund where evidence establishes that the duty incidence was not passed to buyers. A Chartered Accountant certificate, Bills of Entry and sales invoices showing bunker oil was sold below its import value supported non-recovery of even the import cost. Once that material was produced, Revenue needed tangible evidence that buyers bore the duty; recording duty as expenditure in the profit and loss account was insufficient. The High Court upheld the finding that the importer had not passed on the duty incidence, so the refund was properly allowed and no substantial question of law arose.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896