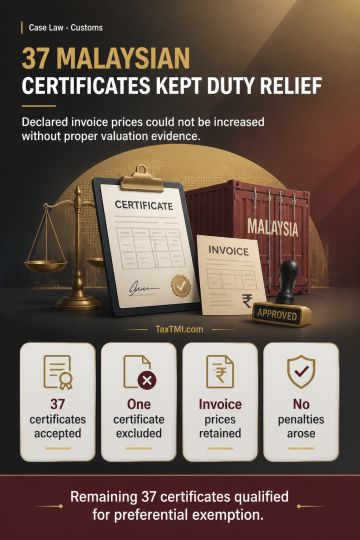
Country of Origin Certificates and declared transaction value supported preferential customs exemption where authenticity and invoice prices remained ...
Online bond platforms may offer overseas-regulated products and tax-specific bonds subject to disclosures, compliance safeguards and revised complianc...
Corporate guarantee valuation permits actual ascertainable commission while barring retroactive application and extended-period penalties for bona fid...
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through w...
Transitioned CENVAT credit may validly satisfy mandatory pre-deposit requirements for legacy service tax appeals through Electronic Credit Ledger debi...
Page of 4894
Press 'Enter' after typing page number.
1981 to 2000 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
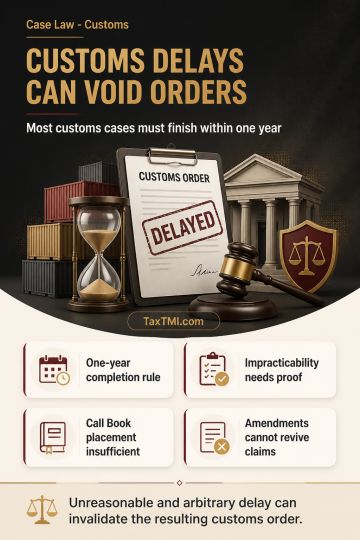
Customs show cause notice adjudication must ordinarily be completed within one year under the unamended framework, unless the officer demonstrates that completion was impracticable. The phrase "where it is possible to do so" does not allow proceedings to remain pending indefinitely or for an unreasonable period. Limitation affects jurisdiction, rendering an order passed beyond the applicable period invalid. Although a procedural amendment may generally operate retrospectively, it cannot revive a stale claim; adjudication must also satisfy any extended period available under the amended regime. Unsupported placement in the Call Book does not justify prolonged delay. Unreasonable and arbitrary delay in adjudication violates Article 14 and can invalidate the resulting customs order.
Customs show cause notice adjudication must ordinarily be completed within one year under the unamended framework, unless the officer demonstrates that completion was impracticable. The phrase "where it is possible to do so" does not allow proceedings to remain pending indefinitely or for an unreasonable period. Limitation affects jurisdiction, rendering an order passed beyond the applicable period invalid. Although a procedural amendment may generally operate retrospectively, it cannot revive a stale claim; adjudication must also satisfy any extended period available under the amended regime. Unsupported placement in the Call Book does not justify prolonged delay. Unreasonable and arbitrary delay in adjudication violates Article 14 and can invalidate the resulting customs order.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894