Blocked input tax credit for resort construction remains unavailable; interest follows actual utilisation, while delayed payment attracts statutory pe...
Duplicate PAN allocation requires record verification and deactivation reasons before assessment-related transactions can be attributed to an assessee...
Faceless assessment safeguards require requested personal hearings and adequate final show-cause response time, failing which reassessment is required...
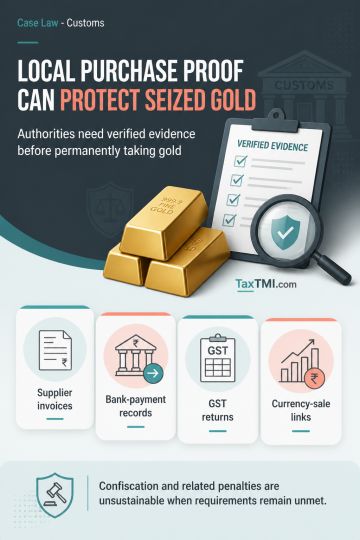
Verifiable evidence of lawful domestic procurement can discharge the claimant's burden for notified gold. Supplier invoices, bank-payment records and GST returns require departmental verification and rebuttal; foreign markings, delayed production of documents and uncorroborated or retracted statements do not by themselves establish smuggling or justify final confiscation. Initial seizure may rest on credible intelligence and reasonable belief, but final confiscation requires proof. Indian currency may be confiscated as smuggled-goods sale proceeds only upon proof of a proximate, identifiable link to specified smuggled goods and knowing dealings. Where these requirements are unmet, confiscation and related penalties are unsustainable.
Verifiable evidence of lawful domestic procurement can discharge the claimant's burden for notified gold. Supplier invoices, bank-payment records and GST returns require departmental verification and rebuttal; foreign markings, delayed production of documents and uncorroborated or retracted statements do not by themselves establish smuggling or justify final confiscation. Initial seizure may rest on credible intelligence and reasonable belief, but final confiscation requires proof. Indian currency may be confiscated as smuggled-goods sale proceeds only upon proof of a proximate, identifiable link to specified smuggled goods and knowing dealings. Where these requirements are unmet, confiscation and related penalties are unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI