Capital Asset Conversion Requires Proven Business Stock Treatment; Paper Consideration in Spousal Flat Transfers Does Not Create Taxable Business Inco...
Human-probability test defeats political donation deduction where banking records mask accommodation-entry fund layering and evidence shows non-genuin...
Commercial property status protects capital-gains exemption when residential-house ownership limits are tested, while agricultural-land character gove...
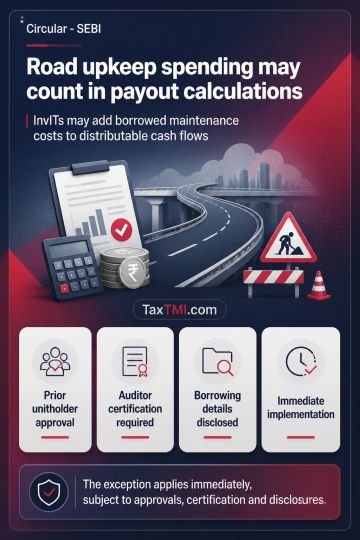
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896