Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
Tariff classification of Digital Axle Counters affirmed as electro-mechanical railway signalling equipment, eliminating duty, confiscation and penalty...
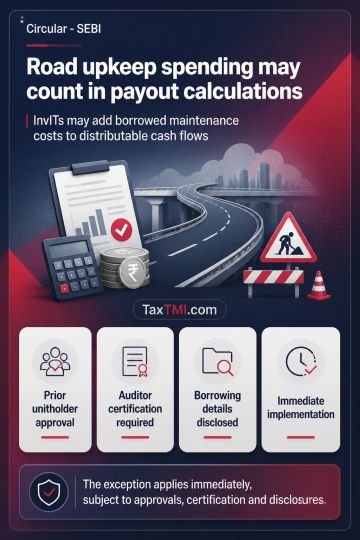
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894