Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
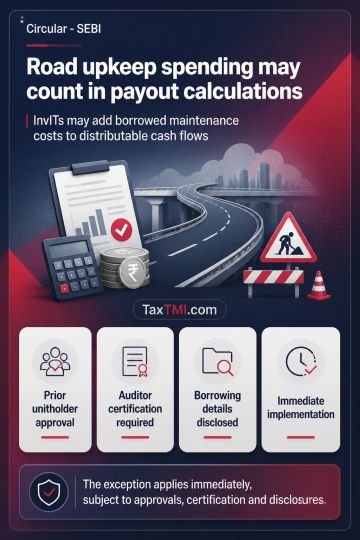
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888