Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
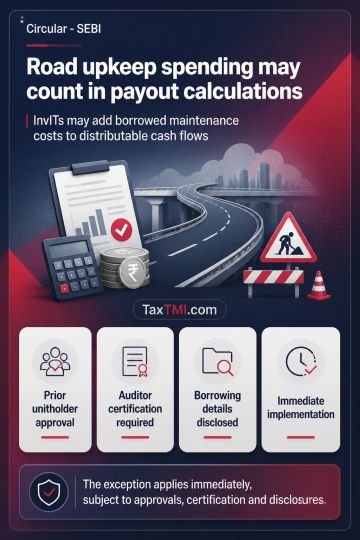
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
InvITs may add back, in calculating net distributable cash flows at both HoldCo/SPV and Trust levels, payments for major maintenance of road projects funded by external borrowings. This exception to the general prohibition on debt-funded cash distributions requires prior unitholder approval for each relevant project, including approval for additional borrowing beyond an approved proposal. Major maintenance must be non-routine expenditure required by the concession agreement. Statutory auditor certification, specified disclosures on borrowing, debt maturity, NDCF and distribution impacts, and disclosures of funding alternatives are required. The revised framework takes effect immediately.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886