Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Approved resolution plan primacy bars rectification claims seeking revival of extinguished equity and consequential monetary or share-based reliefs.
    Natural justice in insolvency-professional discipline requires disclosed material; notices based on extraneous material and ignored defences are vitia...
    Corporate insolvency safeguards resolution-plan approval where no material prejudice, statutory breach, or irregularity is proved.
    Mortgage priority in liquidation preserves earlier pari-passu charges and places unexercised subordinate security within the liquidation estate.
    Prolonged pre-trial custody can override PMLA bail restrictions when delayed trials unjustifiably compromise constitutional personal liberty.
    Redemption fine under the Sabka Vishwas Scheme must be excluded when recalculating legally recoverable settlement dues.
    Development rights transfers treated as immovable property, while construction abatement applies and repeated non-payment permits extended service-tax...
    Signed cheque presumptions support recovery when the drawer provides no cogent evidence of loss or non-liability.
    Change of opinion bars reassessment after scrutiny, while deemed notices must comply with surviving limitation periods.
    GST demand limitation bars late notices unless extended recovery is supported by foundational fraud or suppression facts.
    Fair hearing in budgetary support claims requires an opportunity to explain input tax credit declaration discrepancies before determination.
    Bail in fraudulent input tax credit allegations granted where investigation was nearly complete and further custody unnecessary.
    Input tax credit time limits: Section 16(5) preserves entitlement where the relevant return was filed before the cut-off.
    GST refund mismatch evidence remanded for fresh review, while reconciled trade payables defeat unexplained cash credit addition.
    Competent reassessment sanction is jurisdictional; invalid approval nullifies reassessment, while unproved trading turnover cannot trigger audit penal...
    Additional evidence in commission claims requires fresh consideration when directly relevant, while unsupported uniform interest estimates fail.
    Copyrighted software use without copyright rights is not royalty; equipment supplies remain outside technical-service fees.
    Income Disclosure Scheme immunity and search-material requirements barred further share-transaction additions in unabated assessments under section 15...
    Capital-gains exemption for charitable trusts extends to scheduled-bank fixed deposits and qualifying savings balances from sale proceeds.
    Pecuniary jurisdiction for statutory tax notices makes assessments void when CBDT income-limit instructions are breached
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Judicial review of an interim tender clarification was premature...

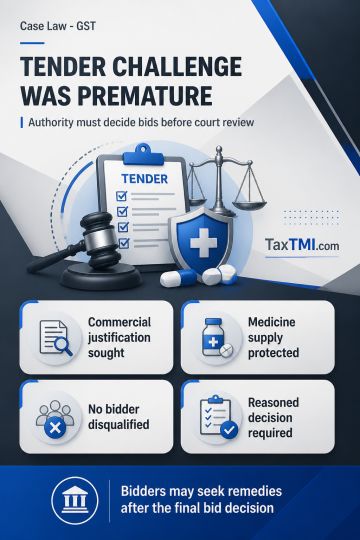
Judicial review of interim tender clarification was premature until the authority considered bidder responses and made a reasoned bid decision.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

GST August 17, 2026 Case Laws HC
Judicial review of an interim tender clarification was premature because the communication sought commercial justification for quoted discounts to assess their sustainability and prevent disruption of medicine supply. Technically qualified bidders had submitted responses and supporting material, but no bid had been rejected or disqualified and no decision on the bids had been made. The tendering authority was required to consider that material and communicate a reasoned decision. The petitions were disposed of, preserving an aggrieved bidder's right to pursue available legal remedies after a final bid decision.

Topics

Acts Income Tax