Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
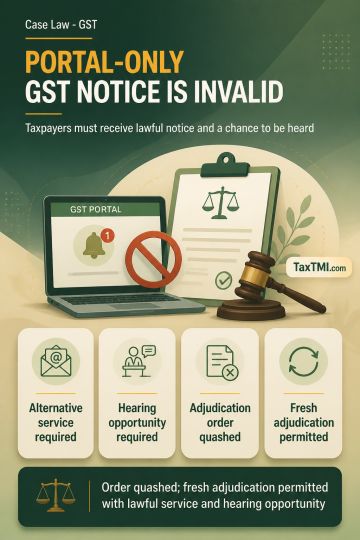
GST portal service of a show-cause notice is invalid after cancellation of registration because the taxpayer cannot be expected to monitor the portal and must be served through an alternative permissible mode. Personal hearing is mandatory under section 75(4) of the CGST Act when requested in writing or when an adverse decision is contemplated, reflecting the audi alteram partem requirement. Failure to provide valid notice and hearing renders GST adjudication vulnerable. The adjudication order was quashed, with fresh notice and adjudication permitted in accordance with law, including a personal hearing if requested.
GST portal service of a show-cause notice is invalid after cancellation of registration because the taxpayer cannot be expected to monitor the portal and must be served through an alternative permissible mode. Personal hearing is mandatory under section 75(4) of the CGST Act when requested in writing or when an adverse decision is contemplated, reflecting the audi alteram partem requirement. Failure to provide valid notice and hearing renders GST adjudication vulnerable. The adjudication order was quashed, with fresh notice and adjudication permitted in accordance with law, including a personal hearing if requested.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881