Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Penalty proceedings under Section 122 of the UPGST Act are...
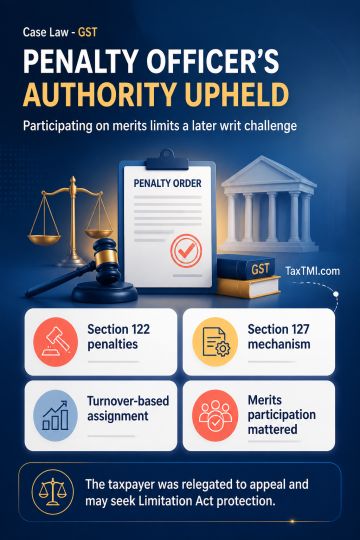
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through writ proceedings.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Penalty proceedings under Section 122 of the UPGST Act are subject to the proper-officer mechanism under Section 127, despite Section 122 not using the expression "proper officer". State circulars assign jurisdiction to the Deputy Commissioner for businesses above the prescribed turnover threshold, supporting the officer's authority to issue the show-cause notice. Although jurisdictional objections may be raised in writ proceedings, discretionary writ relief is ordinarily unavailable where the taxpayer participated on merits without objecting and later seeks to bypass the statutory appeal. The taxpayer was relegated to the appellate remedy and may seek Limitation Act protection if its requirements are met.
Penalty proceedings under Section 122 of the UPGST Act are subject to the proper-officer mechanism under Section 127, despite Section 122 not using the expression "proper officer". State circulars assign jurisdiction to the Deputy Commissioner for businesses above the prescribed turnover threshold, supporting the officer's authority to issue the show-cause notice. Although jurisdictional objections may be raised in writ proceedings, discretionary writ relief is ordinarily unavailable where the taxpayer participated on merits without objecting and later seeks to bypass the statutory appeal. The taxpayer was relegated to the appellate remedy and may seek Limitation Act protection if its requirements are met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886