Building-plan sanction charges require statutory authority; unauthorised fees and GST were quashed, while labour cess must follow prescribed collectio...
Pure-agent exclusion fails where hotel booking facilitators receive third-party services themselves, making entire customer consideration taxable as r...
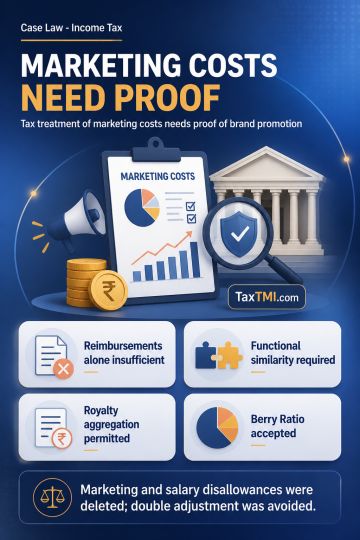
Transfer pricing requires evidence for AMP transactions, functionally reliable comparables, and appropriate aggregation or Berry Ratio benchmarking me...
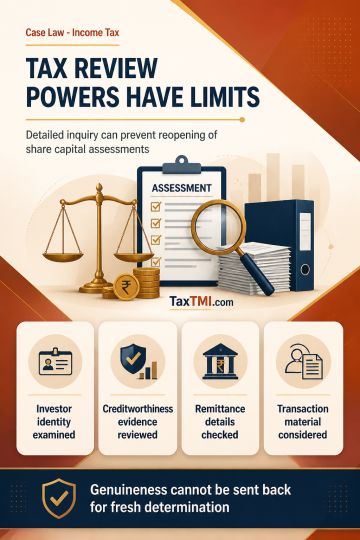
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is establ...
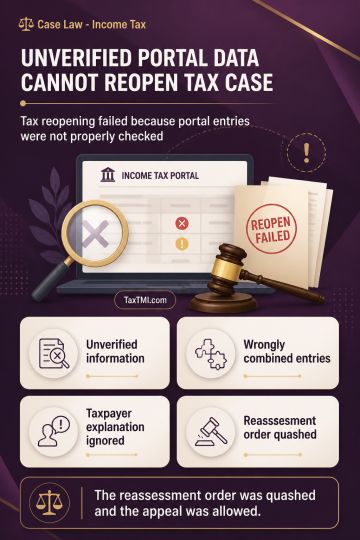
Reassessment jurisdiction fails where unverified portal information is aggregated without examining the taxpayer's explanation or relevance of entries...
Statutory sanction for delayed reassessment requires approval from the prescribed authority; approval by an inferior authority invalidates jurisdictio...
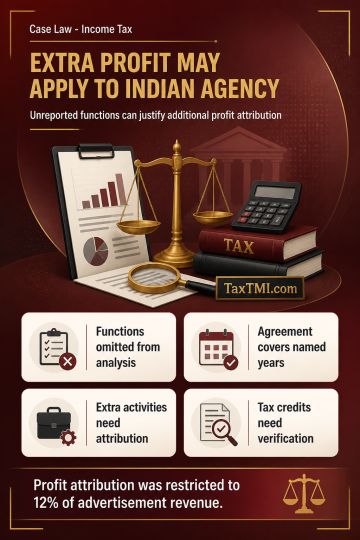
Transfer pricing margin adjustments require matching treatment of non-operating income and related costs, with comparability issues reconsidered on ev...
Page of 4894
Press 'Enter' after typing page number.
2001 to 2020 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Penalty proceedings under Section 122 of the UPGST Act are...
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through writ proceedings.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Penalty proceedings under Section 122 of the UPGST Act are subject to the proper-officer mechanism under Section 127, despite Section 122 not using the expression "proper officer". State circulars assign jurisdiction to the Deputy Commissioner for businesses above the prescribed turnover threshold, supporting the officer's authority to issue the show-cause notice. Although jurisdictional objections may be raised in writ proceedings, discretionary writ relief is ordinarily unavailable where the taxpayer participated on merits without objecting and later seeks to bypass the statutory appeal. The taxpayer was relegated to the appellate remedy and may seek Limitation Act protection if its requirements are met.
Penalty proceedings under Section 122 of the UPGST Act are subject to the proper-officer mechanism under Section 127, despite Section 122 not using the expression "proper officer". State circulars assign jurisdiction to the Deputy Commissioner for businesses above the prescribed turnover threshold, supporting the officer's authority to issue the show-cause notice. Although jurisdictional objections may be raised in writ proceedings, discretionary writ relief is ordinarily unavailable where the taxpayer participated on merits without objecting and later seeks to bypass the statutory appeal. The taxpayer was relegated to the appellate remedy and may seek Limitation Act protection if its requirements are met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894