Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscr...
Anonymous donation classification fails where charitable trusts maintain undisputed donor identity records and evidence corpus contributions' intended...
Transfer pricing method selection favours TNMM where medical-equipment distribution involves substantial post-import value addition and operational ri...
Post-export shipping bill conversion remains available where contemporaneous evidence supports EPCG benefits despite curable procedural omissions and ...
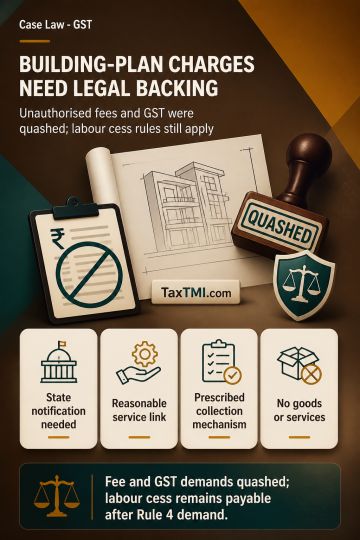
Building-plan sanction charges require statutory authority; unauthorised fees and GST were quashed, while labour cess must follow prescribed collection rules.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Building-plan sanction charges require statutory authority and, as regulatory fees, a reasonable correlation with services rendered. The development authority could exercise Municipal Commissioner powers only upon State notification, while its governing statute did not independently authorise scrutiny fee, ground rent or security deposit; those demands were quashed, subject to the pending writ appeal. Labour welfare cess remained payable, but requiring payment upfront before construction contravened the prescribed collection mechanism for construction extending beyond one year; a fresh demand had to follow Rule 4. Building-plan sanction involved neither a supply of goods nor services, so CGST and SGST on sanction charges were also quashed.
Building-plan sanction charges require statutory authority and, as regulatory fees, a reasonable correlation with services rendered. The development authority could exercise Municipal Commissioner powers only upon State notification, while its governing statute did not independently authorise scrutiny fee, ground rent or security deposit; those demands were quashed, subject to the pending writ appeal. Labour welfare cess remained payable, but requiring payment upfront before construction contravened the prescribed collection mechanism for construction extending beyond one year; a fresh demand had to follow Rule 4. Building-plan sanction involved neither a supply of goods nor services, so CGST and SGST on sanction charges were also quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897