Service permanent establishment requires non-auxiliary services, while arm's-length distributor remuneration precludes further profit attribution in I...
Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscr...
Anonymous donation classification fails where charitable trusts maintain undisputed donor identity records and evidence corpus contributions' intended...
Transfer pricing method selection favours TNMM where medical-equipment distribution involves substantial post-import value addition and operational ri...
Post-export shipping bill conversion remains available where contemporaneous evidence supports EPCG benefits despite curable procedural omissions and ...
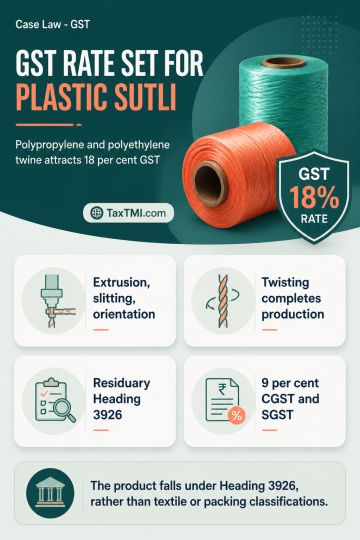
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896