Co-operative deduction eligibility excludes refund and commercial-bank interest, while qualifying co-operative investments require entity-wise verific...
Enhanced tax rate on surrendered unexplained income applies prospectively, while cash-deposit telescoping requires verification of available surrender...
Customs Broker licence proceedings require accurate procedural facts before delay or natural-justice findings can justify setting aside regulatory act...
Provisional assessment finalisation must precede export duty recovery, while redemption fine fails for goods already exported and unavailable for conf...
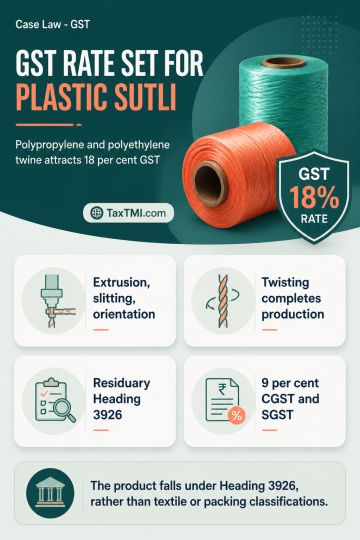
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897