Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
Page of 4897
Press 'Enter' after typing page number.
561 to 580 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
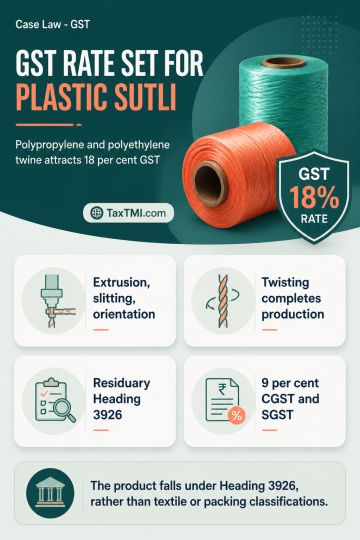
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897