Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
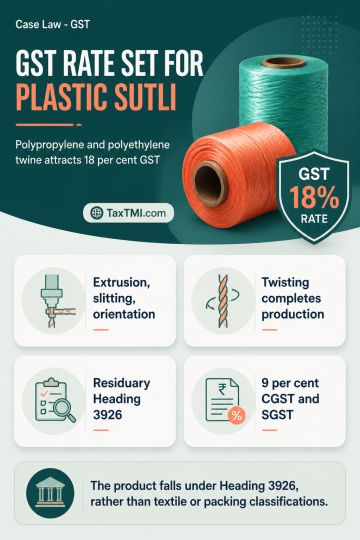
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881