Centralised assessment transfer becomes unwarranted once the searched person's assessment is complete, requiring restoration to the appropriate charge...
Co-operative deduction eligibility excludes refund and commercial-bank interest, while qualifying co-operative investments require entity-wise verific...
Enhanced tax rate on surrendered unexplained income applies prospectively, while cash-deposit telescoping requires verification of available surrender...
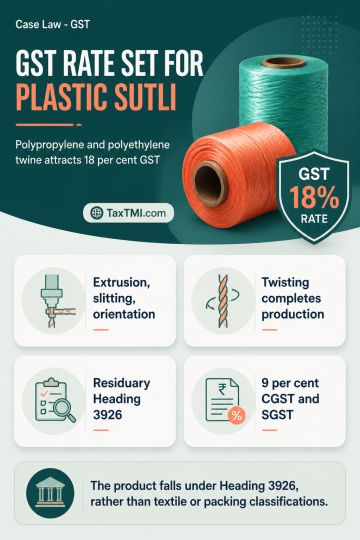
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Polypropylene or polyethylene plastic twine (sutli) manufactured through extrusion, slitting, orientation and twisting is classified as an article of plastics under sub-heading 39269099. The manufacturing process does not make it a textile material for Heading 5607, and the product is not a container or packing article within Heading 3923. In the absence of a more specific Chapter 39 classification, residuary Heading 3926 applies. Plastic twine under Heading 3926 attracts GST at 18 per cent, comprising 9 per cent CGST and 9 per cent SGST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927