Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
Pure-agent exclusion under Rule 33 requires satisfaction of...
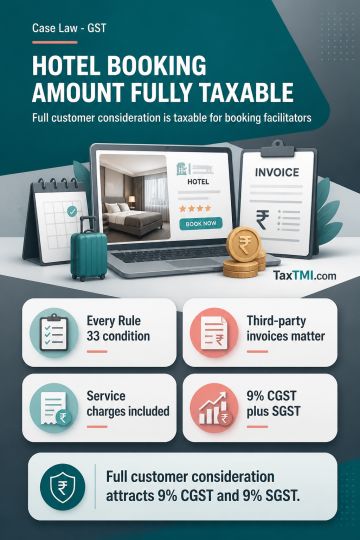
Pure-agent exclusion fails where hotel booking facilitators receive third-party services themselves, making entire customer consideration taxable as reservation services.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Pure-agent exclusion under Rule 33 requires satisfaction of every prescribed condition, including contractual authority to procure third-party services on the end customer's behalf. Hotel booking charges could not be excluded where the third-party booking agent invoiced the facilitator, indicating that it received and used the service in supplying its own hotel booking service, and where the recovered amount included a service charge not known to or authorised by the customer. The booking service is classified under SAC 998552 as reservation services for accommodation, cruises and package tours. CGST and SGST apply at 9% each on the entire consideration received from end customers.
Pure-agent exclusion under Rule 33 requires satisfaction of every prescribed condition, including contractual authority to procure third-party services on the end customer's behalf. Hotel booking charges could not be excluded where the third-party booking agent invoiced the facilitator, indicating that it received and used the service in supplying its own hotel booking service, and where the recovered amount included a service charge not known to or authorised by the customer. The booking service is classified under SAC 998552 as reservation services for accommodation, cruises and package tours. CGST and SGST apply at 9% each on the entire consideration received from end customers.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897