Country of Origin Certificates and declared transaction value supported preferential customs exemption where authenticity and invoice prices remained ...
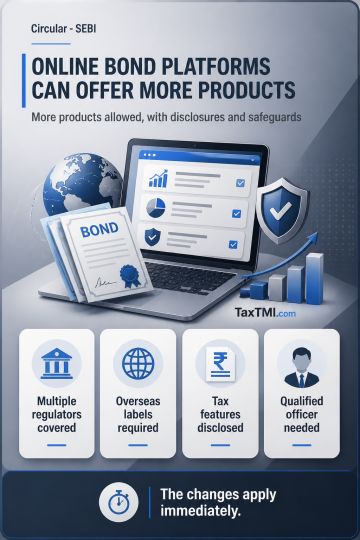
Online bond platforms may offer overseas-regulated products and tax-specific bonds subject to disclosures, compliance safeguards and revised complianc...
Corporate guarantee valuation permits actual ascertainable commission while barring retroactive application and extended-period penalties for bona fid...
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through w...
Transitioned CENVAT credit may validly satisfy mandatory pre-deposit requirements for legacy service tax appeals through Electronic Credit Ledger debi...
Page of 4896
Press 'Enter' after typing page number.
2021 to 2040 of 97907 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Pure-agent exclusion under Rule 33 requires satisfaction of...
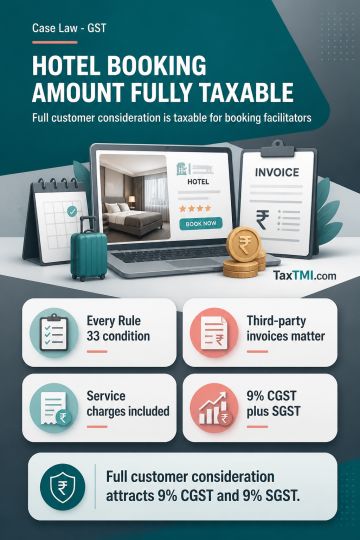
Pure-agent exclusion fails where hotel booking facilitators receive third-party services themselves, making entire customer consideration taxable as reservation services.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Pure-agent exclusion under Rule 33 requires satisfaction of every prescribed condition, including contractual authority to procure third-party services on the end customer's behalf. Hotel booking charges could not be excluded where the third-party booking agent invoiced the facilitator, indicating that it received and used the service in supplying its own hotel booking service, and where the recovered amount included a service charge not known to or authorised by the customer. The booking service is classified under SAC 998552 as reservation services for accommodation, cruises and package tours. CGST and SGST apply at 9% each on the entire consideration received from end customers.
Pure-agent exclusion under Rule 33 requires satisfaction of every prescribed condition, including contractual authority to procure third-party services on the end customer's behalf. Hotel booking charges could not be excluded where the third-party booking agent invoiced the facilitator, indicating that it received and used the service in supplying its own hotel booking service, and where the recovered amount included a service charge not known to or authorised by the customer. The booking service is classified under SAC 998552 as reservation services for accommodation, cruises and package tours. CGST and SGST apply at 9% each on the entire consideration received from end customers.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4896