Belated Form 10B filing during Covid-19 cannot defeat charitable exemption where genuine hardship warrants condonation and substantial justice prevail...
Limitation for consequential assessments runs from prescribed authority receipt, while verified purchases cannot be disallowed merely for unanswered s...
Higher depreciation for qualifying commercial vehicles, exempt-income disallowance, research deduction verification, and club-expense treatment clarif...
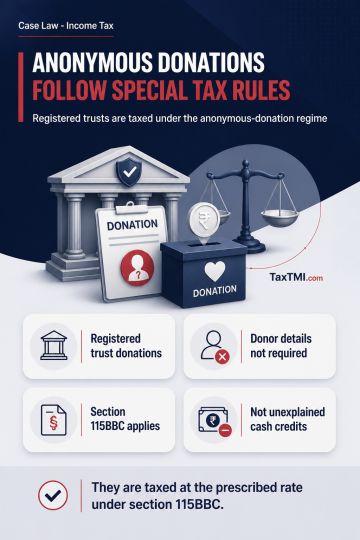
Anonymous donations received by a trust registered under section 12A and claiming exemption under section 11 are specifically governed by section 115BBC. As section 115BBC does not require records establishing anonymous donors' identity, name or address, absence of those particulars cannot justify treating such donations as unexplained cash credits under section 68. The donations are taxable at the prescribed rate under section 115BBC rather than being added as unexplained cash credits.
Anonymous donations received by a trust registered under section 12A and claiming exemption under section 11 are specifically governed by section 115BBC. As section 115BBC does not require records establishing anonymous donors' identity, name or address, absence of those particulars cannot justify treating such donations as unexplained cash credits under section 68. The donations are taxable at the prescribed rate under section 115BBC rather than being added as unexplained cash credits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897