Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
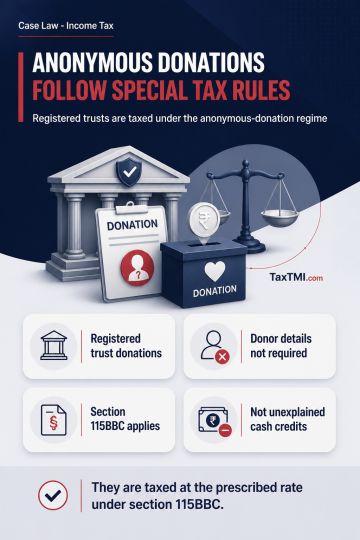
Anonymous donations received by a trust registered under section 12A and claiming exemption under section 11 are specifically governed by section 115BBC. As section 115BBC does not require records establishing anonymous donors' identity, name or address, absence of those particulars cannot justify treating such donations as unexplained cash credits under section 68. The donations are taxable at the prescribed rate under section 115BBC rather than being added as unexplained cash credits.
Anonymous donations received by a trust registered under section 12A and claiming exemption under section 11 are specifically governed by section 115BBC. As section 115BBC does not require records establishing anonymous donors' identity, name or address, absence of those particulars cannot justify treating such donations as unexplained cash credits under section 68. The donations are taxable at the prescribed rate under section 115BBC rather than being added as unexplained cash credits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881