Country of Origin Certificates and declared transaction value supported preferential customs exemption where authenticity and invoice prices remained ...
Online bond platforms may offer overseas-regulated products and tax-specific bonds subject to disclosures, compliance safeguards and revised complianc...
Corporate guarantee valuation permits actual ascertainable commission while barring retroactive application and extended-period penalties for bona fid...
Proper-officer jurisdiction under UPGST penalty provisions upheld; participation on merits prevents bypassing the statutory appellate remedy through w...
Transitioned CENVAT credit may validly satisfy mandatory pre-deposit requirements for legacy service tax appeals through Electronic Credit Ledger debi...
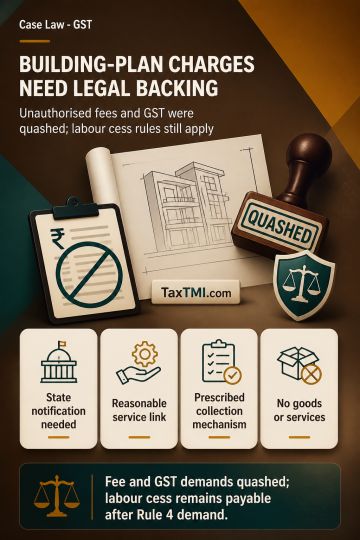
Building-plan sanction charges require statutory authority; unauthorised fees and GST were quashed, while labour cess must follow prescribed collectio...
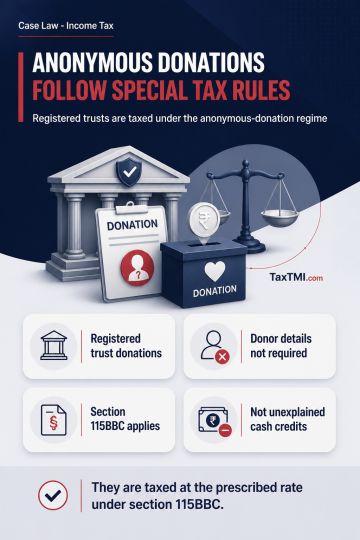
Anonymous donations received by a trust registered under section 12A and claiming exemption under section 11 are specifically governed by section 115BBC. As section 115BBC does not require records establishing anonymous donors' identity, name or address, absence of those particulars cannot justify treating such donations as unexplained cash credits under section 68. The donations are taxable at the prescribed rate under section 115BBC rather than being added as unexplained cash credits.
Anonymous donations received by a trust registered under section 12A and claiming exemption under section 11 are specifically governed by section 115BBC. As section 115BBC does not require records establishing anonymous donors' identity, name or address, absence of those particulars cannot justify treating such donations as unexplained cash credits under section 68. The donations are taxable at the prescribed rate under section 115BBC rather than being added as unexplained cash credits.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897