Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Page of 4894
Press 'Enter' after typing page number.
541 to 560 of 97862 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Transfer-pricing treatment of advertisement, marketing and...
Transfer pricing requires evidence for AMP transactions, functionally reliable comparables, and appropriate aggregation or Berry Ratio benchmarking methods.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
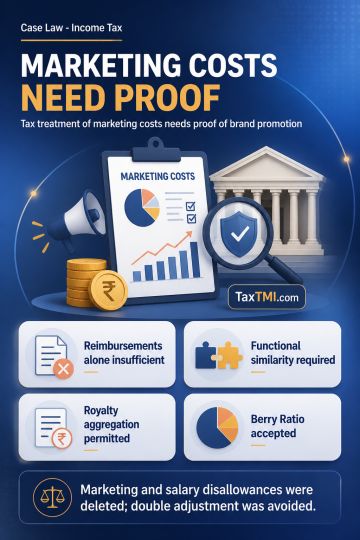
Transfer-pricing treatment of advertisement, marketing and promotion expenditure requires evidence of an arrangement obligating expenditure for an associated enterprise's brand promotion; disclosed marketing reimbursements alone do not create a separate international transaction. Accordingly, AMP adjustments based on the Bright Line Test or intensity-based TNMM were deleted. Comparable selection must reflect functional similarity, with service providers excluded from a predominantly trading-based networking segment and manufacturing comparables adjusted or verified where required. Royalty integral to manufacturing may be aggregated under TNMM where reliable CUP comparables are unavailable, avoiding double adjustment. For low-risk equipment distribution, pass-through cost of goods sold supported use of the Berry Ratio. Expatriate salary disallowance contrary to binding DRP directions was deleted.
Transfer-pricing treatment of advertisement, marketing and promotion expenditure requires evidence of an arrangement obligating expenditure for an associated enterprise's brand promotion; disclosed marketing reimbursements alone do not create a separate international transaction. Accordingly, AMP adjustments based on the Bright Line Test or intensity-based TNMM were deleted. Comparable selection must reflect functional similarity, with service providers excluded from a predominantly trading-based networking segment and manufacturing comparables adjusted or verified where required. Royalty integral to manufacturing may be aggregated under TNMM where reliable CUP comparables are unavailable, avoiding double adjustment. For low-risk equipment distribution, pass-through cost of goods sold supported use of the Berry Ratio. Expatriate salary disallowance contrary to binding DRP directions was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894