Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Transfer-pricing treatment of advertisement, marketing and...
Transfer pricing requires evidence for AMP transactions, functionally reliable comparables, and appropriate aggregation or Berry Ratio benchmarking methods.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
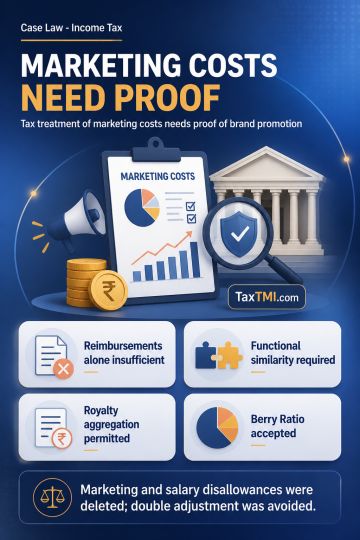
Transfer-pricing treatment of advertisement, marketing and promotion expenditure requires evidence of an arrangement obligating expenditure for an associated enterprise's brand promotion; disclosed marketing reimbursements alone do not create a separate international transaction. Accordingly, AMP adjustments based on the Bright Line Test or intensity-based TNMM were deleted. Comparable selection must reflect functional similarity, with service providers excluded from a predominantly trading-based networking segment and manufacturing comparables adjusted or verified where required. Royalty integral to manufacturing may be aggregated under TNMM where reliable CUP comparables are unavailable, avoiding double adjustment. For low-risk equipment distribution, pass-through cost of goods sold supported use of the Berry Ratio. Expatriate salary disallowance contrary to binding DRP directions was deleted.
Transfer-pricing treatment of advertisement, marketing and promotion expenditure requires evidence of an arrangement obligating expenditure for an associated enterprise's brand promotion; disclosed marketing reimbursements alone do not create a separate international transaction. Accordingly, AMP adjustments based on the Bright Line Test or intensity-based TNMM were deleted. Comparable selection must reflect functional similarity, with service providers excluded from a predominantly trading-based networking segment and manufacturing comparables adjusted or verified where required. Royalty integral to manufacturing may be aggregated under TNMM where reliable CUP comparables are unavailable, avoiding double adjustment. For low-risk equipment distribution, pass-through cost of goods sold supported use of the Berry Ratio. Expatriate salary disallowance contrary to binding DRP directions was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881