Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
Transfer-pricing treatment of advertisement, marketing and...
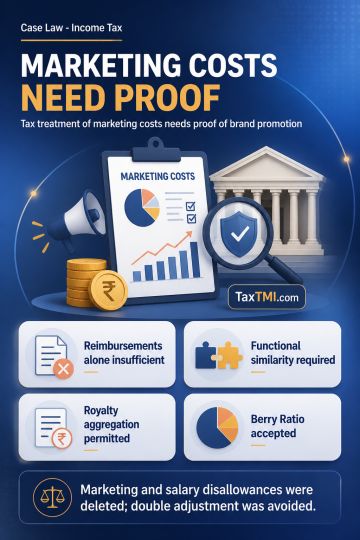
Transfer pricing requires evidence for AMP transactions, functionally reliable comparables, and appropriate aggregation or Berry Ratio benchmarking methods.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Transfer-pricing treatment of advertisement, marketing and promotion expenditure requires evidence of an arrangement obligating expenditure for an associated enterprise's brand promotion; disclosed marketing reimbursements alone do not create a separate international transaction. Accordingly, AMP adjustments based on the Bright Line Test or intensity-based TNMM were deleted. Comparable selection must reflect functional similarity, with service providers excluded from a predominantly trading-based networking segment and manufacturing comparables adjusted or verified where required. Royalty integral to manufacturing may be aggregated under TNMM where reliable CUP comparables are unavailable, avoiding double adjustment. For low-risk equipment distribution, pass-through cost of goods sold supported use of the Berry Ratio. Expatriate salary disallowance contrary to binding DRP directions was deleted.
Transfer-pricing treatment of advertisement, marketing and promotion expenditure requires evidence of an arrangement obligating expenditure for an associated enterprise's brand promotion; disclosed marketing reimbursements alone do not create a separate international transaction. Accordingly, AMP adjustments based on the Bright Line Test or intensity-based TNMM were deleted. Comparable selection must reflect functional similarity, with service providers excluded from a predominantly trading-based networking segment and manufacturing comparables adjusted or verified where required. Royalty integral to manufacturing may be aggregated under TNMM where reliable CUP comparables are unavailable, avoiding double adjustment. For low-risk equipment distribution, pass-through cost of goods sold supported use of the Berry Ratio. Expatriate salary disallowance contrary to binding DRP directions was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881