Transfer-pricing comparability permits fresh objections and filters where software service comparables are functionally unsuitable for arm's-length pr...
Territorial rendering requirement excludes China-based management and consultancy services from fees for technical services under the India-China DTAA...
FEMA borrowing restrictions bind charitable trusts, and civil penalties apply without proving intent for delayed repayment of non-resident rupee loans...
Revision under section 263 cannot rest merely on a view that the...
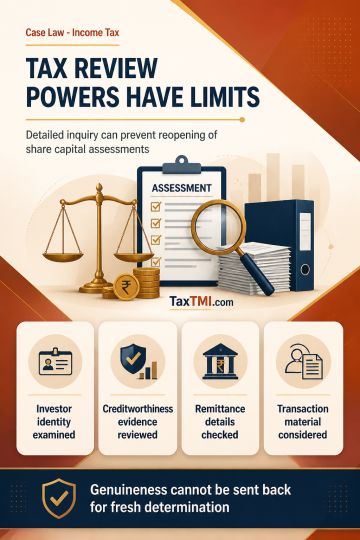
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is established.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881