Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Page of 4884
Press 'Enter' after typing page number.
261 to 280 of 97661 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Revision under section 263 cannot rest merely on a view that the...
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is established.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
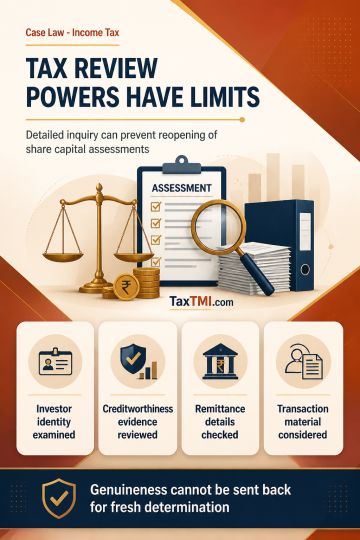
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884