Infrastructure-development deduction remains available to EPC contractors when substantive statutory conditions outweigh contractor labels in agreemen...
Explained Investment Sources: documented gifts and traceable salary savings supported deletion of additions for property and mutual-fund SIP investmen...
Internal comparable pricing supports arm's-length interest on compulsorily convertible debentures, preventing their recharacterisation as equity for t...
Nominee director protection shields independent financial-institution appointees from criminal liability where they lack involvement in deposit defaul...
Page of 4884
Press 'Enter' after typing page number.
241 to 260 of 97661 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Revision under section 263 cannot rest merely on a view that the...
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is established.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
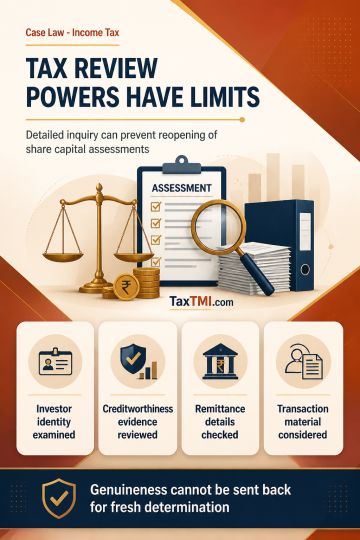
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884