Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscr...
Anonymous donation classification fails where charitable trusts maintain undisputed donor identity records and evidence corpus contributions' intended...
Transfer pricing method selection favours TNMM where medical-equipment distribution involves substantial post-import value addition and operational ri...
Post-export shipping bill conversion remains available where contemporaneous evidence supports EPCG benefits despite curable procedural omissions and ...
Revision under section 263 cannot rest merely on a view that the...
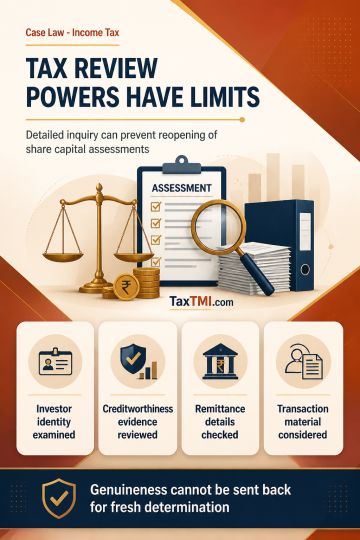
Revisionary jurisdiction cannot reopen share capital assessments where adequate inquiry supports a permissible view and no independent error is established.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Revision under section 263 cannot rest merely on a view that the Assessing Officer should have conducted a deeper inquiry into share capital received from an existing non-resident shareholder. Where the assessment record shows detailed queries and supporting material on the investor's identity, creditworthiness, remittance and transaction, an assessment order need not expressly record every inquiry to establish application of mind. Revisionary jurisdiction does not permit re-examination where the Assessing Officer adopted a permissible view after inquiry. The revisionary authority must undertake at least minimal independent inquiry and clearly establish that the assessment is both erroneous and prejudicial to Revenue; it cannot remand genuineness for fresh determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897