Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
Statutory sanction by the authority specified under section...
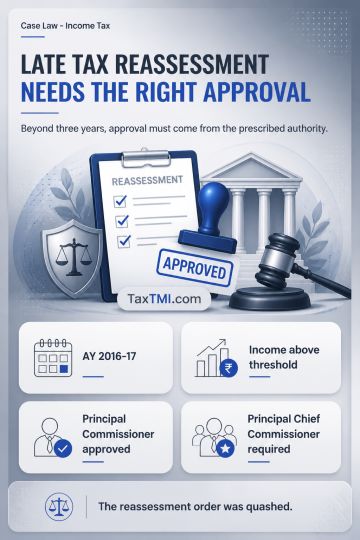
Statutory sanction for delayed reassessment requires approval from the prescribed authority; approval by an inferior authority invalidates jurisdiction.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Statutory sanction by the authority specified under section 151(ii) is a jurisdictional precondition for reassessment notices issued beyond three years where alleged escaped income exceeds the prescribed threshold. For AY 2016-17, approval from the Principal Commissioner did not satisfy the requirement for approval from the Principal Chief Commissioner. The defect invalidated the assumption of reassessment jurisdiction, resulting in the reassessment order being quashed.
Statutory sanction by the authority specified under section 151(ii) is a jurisdictional precondition for reassessment notices issued beyond three years where alleged escaped income exceeds the prescribed threshold. For AY 2016-17, approval from the Principal Commissioner did not satisfy the requirement for approval from the Principal Chief Commissioner. The defect invalidated the assumption of reassessment jurisdiction, resulting in the reassessment order being quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897