Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Page of 4881
Press 'Enter' after typing page number.
281 to 300 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Declared export transaction value cannot be rejected merely on...
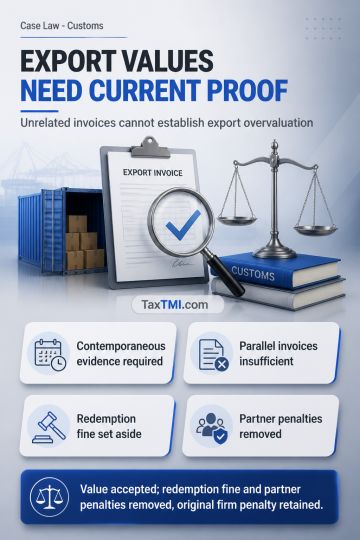
Export valuation requires contemporaneous evidence; unrelated invoices cannot prove overvaluation, and dual penalties on firm and partner are impermissible.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Declared export transaction value cannot be rejected merely on parallel or pro-forma invoices unrelated to the disputed consignment. Rejection requires contemporaneous prices of identical goods, market inquiry, or cogent evidence of manipulation such as financial flow-back from the foreign buyer. As no such evidence established overvaluation, the declared value was accepted and redemption fine was set aside because the goods had already been exported. Penalties on both a partnership firm and its partner for the same infraction amount to impermissible double punishment, since the firm is not distinct from its partners for this purpose. The original penalty on the firm was retained for past parallel invoices, while enhanced penalties and all partner penalties were removed.
Declared export transaction value cannot be rejected merely on parallel or pro-forma invoices unrelated to the disputed consignment. Rejection requires contemporaneous prices of identical goods, market inquiry, or cogent evidence of manipulation such as financial flow-back from the foreign buyer. As no such evidence established overvaluation, the declared value was accepted and redemption fine was set aside because the goods had already been exported. Penalties on both a partnership firm and its partner for the same infraction amount to impermissible double punishment, since the firm is not distinct from its partners for this purpose. The original penalty on the firm was retained for past parallel invoices, while enhanced penalties and all partner penalties were removed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881