Unverified Insight Portal Information Cannot Justify Reassessment Without a Verified Taxpayer-Specific Income-Escape Nexus or Demonstrated Application...
Assessing Officer jurisdiction after statutory transfer invalidates reassessment notices issued by transferor officers and nullifies resulting proceed...
Consequential appeal-effect orders must implement rectification deleting working-capital adjustments and reconsider the resulting arm's-length range c...
Discounted cash flow valuation protects share premium where projections are reasonable, while audited book expenses defeat unexplained-expenditure add...
Section 54 construction relief survives pre-transfer commencement when completion occurs within the statutory period, excluding ineligible spouse-owne...
Declared export transaction value cannot be rejected merely on...
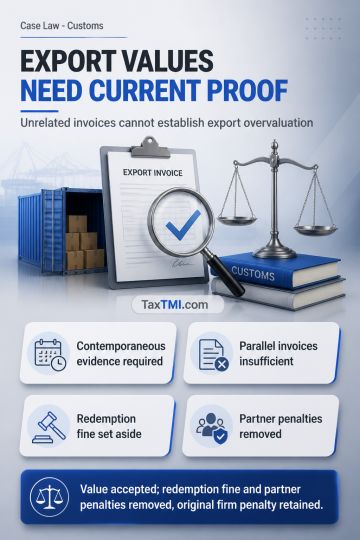
Export valuation requires contemporaneous evidence; unrelated invoices cannot prove overvaluation, and dual penalties on firm and partner are impermissible.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Declared export transaction value cannot be rejected merely on parallel or pro-forma invoices unrelated to the disputed consignment. Rejection requires contemporaneous prices of identical goods, market inquiry, or cogent evidence of manipulation such as financial flow-back from the foreign buyer. As no such evidence established overvaluation, the declared value was accepted and redemption fine was set aside because the goods had already been exported. Penalties on both a partnership firm and its partner for the same infraction amount to impermissible double punishment, since the firm is not distinct from its partners for this purpose. The original penalty on the firm was retained for past parallel invoices, while enhanced penalties and all partner penalties were removed.
Declared export transaction value cannot be rejected merely on parallel or pro-forma invoices unrelated to the disputed consignment. Rejection requires contemporaneous prices of identical goods, market inquiry, or cogent evidence of manipulation such as financial flow-back from the foreign buyer. As no such evidence established overvaluation, the declared value was accepted and redemption fine was set aside because the goods had already been exported. Penalties on both a partnership firm and its partner for the same infraction amount to impermissible double punishment, since the firm is not distinct from its partners for this purpose. The original penalty on the firm was retained for past parallel invoices, while enhanced penalties and all partner penalties were removed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881