Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
Diagnostic microcuvette classification follows sole-use analytical function, placing specialised disposable cuvettes with their analyser rather than g...
Customs Broker licensing proceedings fail when their offence-report foundation collapses and authorisation, advisory, and KYC duties remain unbreached...
Tariff classification of Digital Axle Counters affirmed as electro-mechanical railway signalling equipment, eliminating duty, confiscation and penalty...
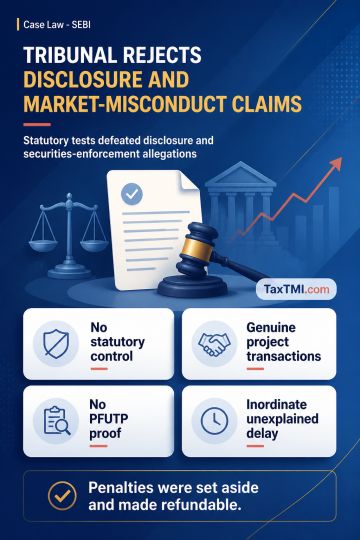
Statutory associate-company criteria governed whether the group company required consolidation and related-party disclosures. The Tribunal majority found no prescribed voting threshold, agreement, control, or participation in business decisions; accounting standards could supplement but not override the statutory definition. Consolidation and related-party disclosure contraventions therefore failed. The majority also found the real-estate bulk-sale memoranda and underlying projects genuine, with no proof that common personnel, funding arrangements, accounting differences, or weak finances established a sham scheme, market impact, unlawful gain, or PFUTP violation. Securities-enforcement proceedings were further initiated after inordinate, unexplained delay following completed transactions. The appeals succeeded, penalties were set aside and refundable; the Presiding Officer dissented.
Statutory associate-company criteria governed whether the group company required consolidation and related-party disclosures. The Tribunal majority found no prescribed voting threshold, agreement, control, or participation in business decisions; accounting standards could supplement but not override the statutory definition. Consolidation and related-party disclosure contraventions therefore failed. The majority also found the real-estate bulk-sale memoranda and underlying projects genuine, with no proof that common personnel, funding arrangements, accounting differences, or weak finances established a sham scheme, market impact, unlawful gain, or PFUTP violation. Securities-enforcement proceedings were further initiated after inordinate, unexplained delay following completed transactions. The appeals succeeded, penalties were set aside and refundable; the Presiding Officer dissented.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888