Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
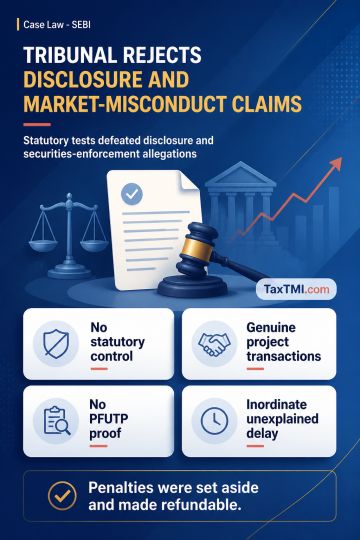
Statutory associate-company criteria governed whether the group company required consolidation and related-party disclosures. The Tribunal majority found no prescribed voting threshold, agreement, control, or participation in business decisions; accounting standards could supplement but not override the statutory definition. Consolidation and related-party disclosure contraventions therefore failed. The majority also found the real-estate bulk-sale memoranda and underlying projects genuine, with no proof that common personnel, funding arrangements, accounting differences, or weak finances established a sham scheme, market impact, unlawful gain, or PFUTP violation. Securities-enforcement proceedings were further initiated after inordinate, unexplained delay following completed transactions. The appeals succeeded, penalties were set aside and refundable; the Presiding Officer dissented.
Statutory associate-company criteria governed whether the group company required consolidation and related-party disclosures. The Tribunal majority found no prescribed voting threshold, agreement, control, or participation in business decisions; accounting standards could supplement but not override the statutory definition. Consolidation and related-party disclosure contraventions therefore failed. The majority also found the real-estate bulk-sale memoranda and underlying projects genuine, with no proof that common personnel, funding arrangements, accounting differences, or weak finances established a sham scheme, market impact, unlawful gain, or PFUTP violation. Securities-enforcement proceedings were further initiated after inordinate, unexplained delay following completed transactions. The appeals succeeded, penalties were set aside and refundable; the Presiding Officer dissented.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886