Ratification of resignation acceptance validates separation retrospectively, while withdrawal may be refused through reasoned administrative discretio...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements fr...
Alternative GST remedy permitted protective writ intervention for ex parte adjudication, preserving independent appellate review of input tax credit d...
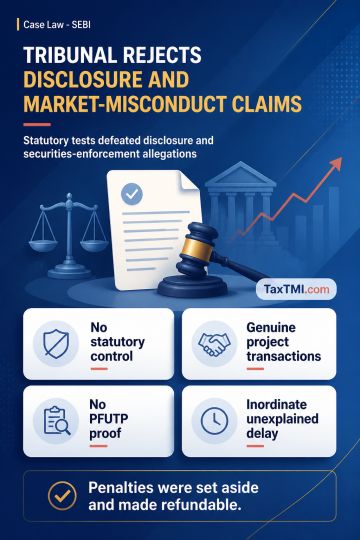
Statutory associate-company criteria governed whether the group company required consolidation and related-party disclosures. The Tribunal majority found no prescribed voting threshold, agreement, control, or participation in business decisions; accounting standards could supplement but not override the statutory definition. Consolidation and related-party disclosure contraventions therefore failed. The majority also found the real-estate bulk-sale memoranda and underlying projects genuine, with no proof that common personnel, funding arrangements, accounting differences, or weak finances established a sham scheme, market impact, unlawful gain, or PFUTP violation. Securities-enforcement proceedings were further initiated after inordinate, unexplained delay following completed transactions. The appeals succeeded, penalties were set aside and refundable; the Presiding Officer dissented.
Statutory associate-company criteria governed whether the group company required consolidation and related-party disclosures. The Tribunal majority found no prescribed voting threshold, agreement, control, or participation in business decisions; accounting standards could supplement but not override the statutory definition. Consolidation and related-party disclosure contraventions therefore failed. The majority also found the real-estate bulk-sale memoranda and underlying projects genuine, with no proof that common personnel, funding arrangements, accounting differences, or weak finances established a sham scheme, market impact, unlawful gain, or PFUTP violation. Securities-enforcement proceedings were further initiated after inordinate, unexplained delay following completed transactions. The appeals succeeded, penalties were set aside and refundable; the Presiding Officer dissented.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897