Embezzlement losses in charitable institutions remain allowable when misappropriation is established, irrecoverable, and not a specified-person benefi...
National long-distance undertaking status supports deduction where separately licensed infrastructure, resources, revenue, and expenditure establish c...
Agency reimbursement income follows contractual deposit-liability computation, while pending deposit collections do not constitute deemed-dividend loa...
Membership-consent thresholds for oppression petitions are satisfied by unchallenged voter-list consents, while unsupported forgery claims require pro...
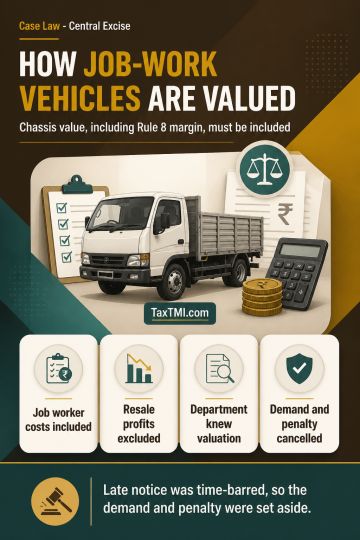
Assessable value of a body-built motor vehicle manufactured on job work includes the chassis value on which duty was paid, including the additional margin applied under Rule 8, together with the job worker's material cost, expenses and profit. The manufacturer's anticipated resale profit and post-receipt expenses remain excluded. Although this valuation component was required to be included, extended limitation for duty recovery requires fraud, collusion, wilful misstatement, wilful suppression, or intent to evade duty. Departmental knowledge that the chassis had been valued at 110% of manufacturing cost precluded treating the job worker's omission as wilful suppression. A notice issued beyond the ordinary limitation period was therefore time-barred, resulting in the demand and penalty being set aside.
Assessable value of a body-built motor vehicle manufactured on job work includes the chassis value on which duty was paid, including the additional margin applied under Rule 8, together with the job worker's material cost, expenses and profit. The manufacturer's anticipated resale profit and post-receipt expenses remain excluded. Although this valuation component was required to be included, extended limitation for duty recovery requires fraud, collusion, wilful misstatement, wilful suppression, or intent to evade duty. Departmental knowledge that the chassis had been valued at 110% of manufacturing cost precluded treating the job worker's omission as wilful suppression. A notice issued beyond the ordinary limitation period was therefore time-barred, resulting in the demand and penalty being set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881