Make-available condition excludes standard SaaS subscription receipts where customers receive no independently usable technical knowledge after subscr...
Anonymous donation classification fails where charitable trusts maintain undisputed donor identity records and evidence corpus contributions' intended...
Transfer pricing method selection favours TNMM where medical-equipment distribution involves substantial post-import value addition and operational ri...
Post-export shipping bill conversion remains available where contemporaneous evidence supports EPCG benefits despite curable procedural omissions and ...
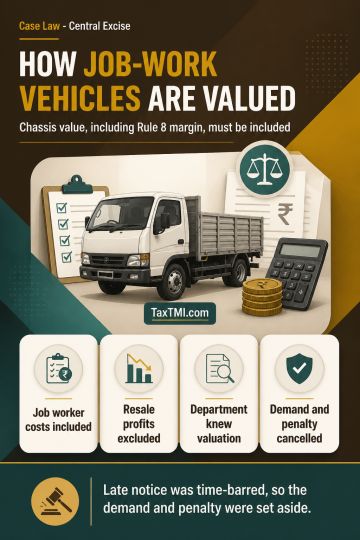
Assessable value of a body-built motor vehicle manufactured on job work includes the chassis value on which duty was paid, including the additional margin applied under Rule 8, together with the job worker's material cost, expenses and profit. The manufacturer's anticipated resale profit and post-receipt expenses remain excluded. Although this valuation component was required to be included, extended limitation for duty recovery requires fraud, collusion, wilful misstatement, wilful suppression, or intent to evade duty. Departmental knowledge that the chassis had been valued at 110% of manufacturing cost precluded treating the job worker's omission as wilful suppression. A notice issued beyond the ordinary limitation period was therefore time-barred, resulting in the demand and penalty being set aside.
Assessable value of a body-built motor vehicle manufactured on job work includes the chassis value on which duty was paid, including the additional margin applied under Rule 8, together with the job worker's material cost, expenses and profit. The manufacturer's anticipated resale profit and post-receipt expenses remain excluded. Although this valuation component was required to be included, extended limitation for duty recovery requires fraud, collusion, wilful misstatement, wilful suppression, or intent to evade duty. Departmental knowledge that the chassis had been valued at 110% of manufacturing cost precluded treating the job worker's omission as wilful suppression. A notice issued beyond the ordinary limitation period was therefore time-barred, resulting in the demand and penalty being set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897