Fraud classification show-cause notices founded on inconclusive forensic audit material cannot sustain action, permitting fresh proceedings on conclus...
Appellate enhancement limits protect against new income sources, while documented credits and prior-year investments resist unexplained-income additio...
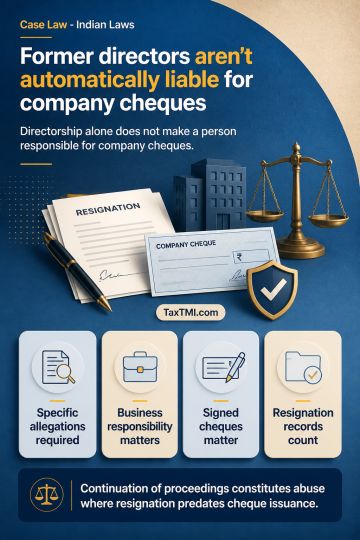
Section 141 of the Negotiable Instruments Act does not impose automatic vicarious liability on a director merely because of directorship. A cheque-dishonour complaint must specifically allege that the person was in charge of and responsible for the company's business when the offence occurred, or that it resulted from that person's consent, connivance or neglect. General allegations are inadequate, particularly where the person neither signed the cheques nor remained a director when they were issued and dishonoured. Statutory records establishing resignation before issuance of the cheques negate such liability, and continuation of proceedings in those circumstances constitutes abuse of process.
Section 141 of the Negotiable Instruments Act does not impose automatic vicarious liability on a director merely because of directorship. A cheque-dishonour complaint must specifically allege that the person was in charge of and responsible for the company's business when the offence occurred, or that it resulted from that person's consent, connivance or neglect. General allegations are inadequate, particularly where the person neither signed the cheques nor remained a director when they were issued and dishonoured. Statutory records establishing resignation before issuance of the cheques negate such liability, and continuation of proceedings in those circumstances constitutes abuse of process.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884