ODR arbitration participation remains mandatory after failed conciliation, while jurisdictional and maintainability objections stay available before t...
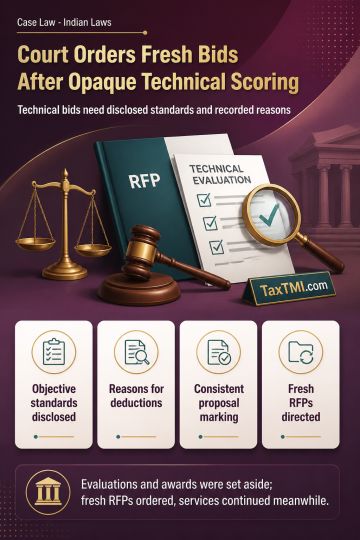
Transparency in technical bid evaluation requires disclosed standards and recorded reasons; opaque scoring invalidated tender awards and required fres...
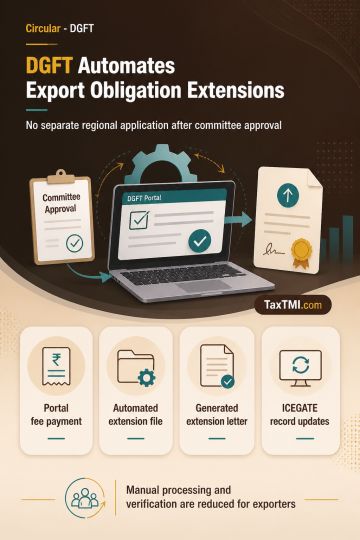
Automated export obligation extensions remove separate regional applications after committee approval for Advance Authorisation and EPCG authorisation...
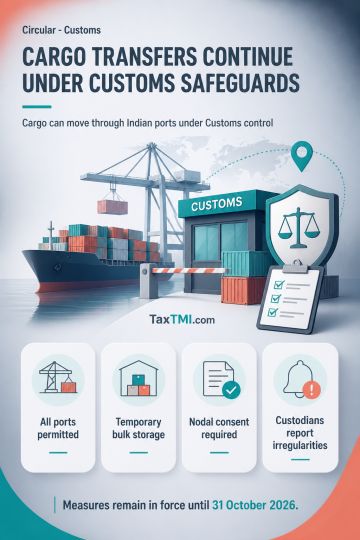
International cargo transhipment through Indian ports continues with Customs-controlled storage, re-export safeguards, and coordinated multi-station m...
Nature-dependent electricity contracts receive new Ind AS accounting, hedge designation, transition and financial-statement disclosure requirements from annual periods beginning April 2026.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Companies (Indian Accounting Standards) Amendment Rules, 2026 amend Ind AS 101, 107, 109, 110 and 7, taking effect on publication in the Official Gazette. The amendments establish accounting, hedge-accounting, transition and disclosure requirements for contracts referencing nature-dependent electricity, including assessment of expected usage, net-purchaser status, financial-statement disclosures and optional fair-value-through-profit-or-loss designation at initial application. They also revise financial-instrument classification and measurement guidance, including contingent cash flows, basic lending arrangements, non-recourse features, electronic-payment derecognition and related disclosures. Most specified amendments apply to annual reporting periods beginning on or after 1 April 2026, with retrospective application subject to prescribed transition reliefs and opening-equity adjustments where comparative periods are not restated.
Companies (Indian Accounting Standards) Amendment Rules, 2026 amend Ind AS 101, 107, 109, 110 and 7, taking effect on publication in the Official Gazette. The amendments establish accounting, hedge-accounting, transition and disclosure requirements for contracts referencing nature-dependent electricity, including assessment of expected usage, net-purchaser status, financial-statement disclosures and optional fair-value-through-profit-or-loss designation at initial application. They also revise financial-instrument classification and measurement guidance, including contingent cash flows, basic lending arrangements, non-recourse features, electronic-payment derecognition and related disclosures. Most specified amendments apply to annual reporting periods beginning on or after 1 April 2026, with retrospective application subject to prescribed transition reliefs and opening-equity adjustments where comparative periods are not restated.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932